
American debt loads are accelerating, driven by extremely low interest rates in the pandemic recovery. An unexpected housing boom demonstrates how consumers are taking advantage of the economic downturn, and between May and June, pending home sales rose by 16 percent. Delinquency rates rose steeply on FHA-insured subprime mortgages in lockstep with as many as 17 percent of said mortgages delinquent.
Although total household debt declined slightly in Q2 2020, the coinciding effects of unemployment caused stress on Americans. And while the average credit score increased in the U.S. to an all-time high of 703 this year, the ability to acquire new loans has become more difficult as FICO introduced a new resiliency index.
Consumer credit challenges can leave potential car buyers out in the cold, unable to obtain competitive financing. Buy-here-pay-here (BHPH) lending is a solution that may not be seen as favorable by dealers, but it can be a profitable way to sell cars to those who suddenly can’t obtain financing.
BHPH Seen as Picking Low-Hanging Fruit
For both dealers and consumers, BHPH financing can appear like it’s taking advantage of shoppers who are already credit-challenged. It’s a favorite tool for car lots selling less-than-desirable cars to less-than-qualified buyers, but the reputation for BHPH auto loans is unwarranted.
Seedy sellers have caused an association with the word ‘fraud’ and ‘scam’, but buy-here-pay-here loans are beneficial for a certain segment of consumers, particularly with the new resiliency index. 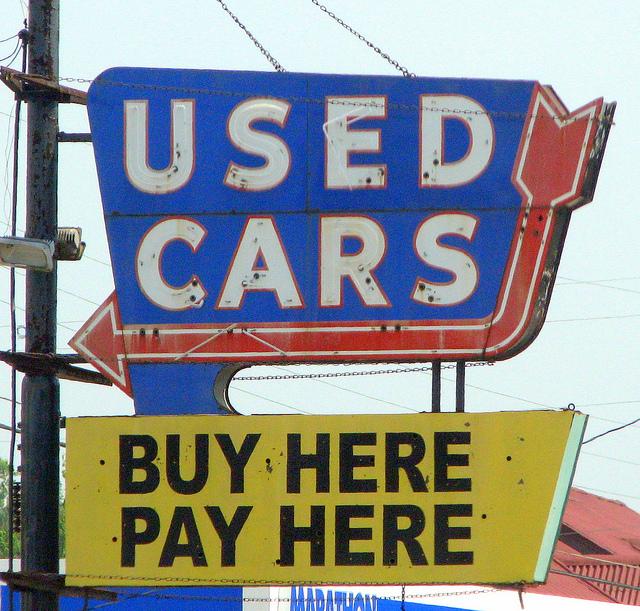
Backed Loans for Dealers
Agora Data, Inc. provides predictive loan tech for sellers, and a recent press release announced that they will now offer AgoraCapital, low-cost financing through capital markets for dealers that offer BHPH financing. While the market is far from saturated, there are options available for dealers to provide BHPH auto loans to customers even when they don’t have the liquid assets to do so.
Financial backing is particularly useful during and post-COVID as small and medium-sized businesses, including dealerships, are stretched thin on capital. This market that offers a relatively high return on investment wouldn’t be possible for many without access to funding.
Should Dealers Offer BHPH Options?
There are certainly dealers who offer out-of-pocket BHPH financing for less-qualified buyers. These loans are almost guaranteed to come with high interest rates and terms that lean in the dealership’s favor, particularly as the dealer carries all of the risk. The optics of providing BHPH options at a franchised or highly visible and reputable independent dealership is what’s in question more than anything.
Dealers who offer in-house financing to under-qualified buyers that will either struggle to make ends meet or have an extremely high likelihood of the vehicle being repossessed could find that their reputation is tarnished from the practice. However, when buyers who would otherwise be qualified, subject to subprime rates, or may be marginal approvals are involved, BHPH could be a service that improves the dealership’s standing.
Dealers have to be careful navigating BHPH financing, especially since it’s viewed from two polar-opposite positions of beneficial and exploitive. Terms need to explained clearly and clientele need to be chosen carefully to ensure neither the dealership is seen as taking advantage of a customer nor the buyer is truly unqualified for the loan.
Did you enjoy this article from Jason Unrau? Read other articles from him here.
 Be sure to follow us on Facebook and Twitter to stay up to date or catch-up on all of our podcasts on demand.
While you’re here, don’t forget to subscribe to our email newsletter for all the latest auto industry news from CBT News.