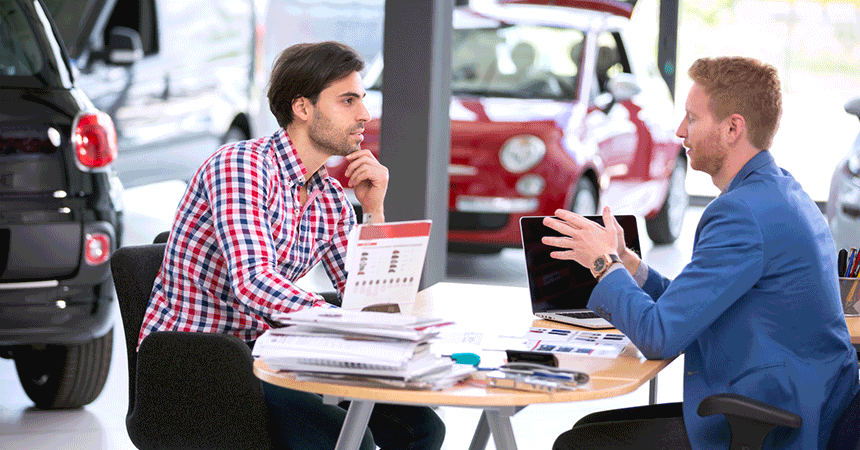
In the years since the Consumer Finance Protection Bureau (CFPB) began to strike fear in the hearts of dealers everywhere, there have been a lot of changes in how F&I departments handle the heavy compliance burden they have on every deal they write. Yet even in the wake of such a massive change in how this profit center does business, there are still reports of risky F&I practices that are resulting in fines, and for some, jail time for those directly involved. What are some examples of the unethical practices that are prominent on the ‘regulatory radar’ these days and how can a dealer avoid the penalties they could incur?
Common F&I practices that will put your dealership at risk:
- ‘Internet only’ rate specials that can be seen as discriminatory against buyers that have no web access. California has laws prohibiting this practice, which is common as the Internet increasingly becomes vital to a dealer’s business.
- Not securing all signatures at the time of delivery. Some dealers are still getting caught with unsigned paperwork or signed blank documents used for unauthorized product placement after the sale.
- ‘Jamming’ or ‘payment packing’ that has F&I personnel adding extra products to the deal and in some case, leaving it off the contract altogether. GAP, etching, extended warranties, etc. are some of the products that can be arbitrarily added into the payment without the buyer knowing.
- Charging higher rates for different borrowers based on race/color/sex/age, etc. It seems every few weeks there is another headline regarding a dealer accused of ‘disparate impact’ discrimination on interest rates.
According to industry experts at NADA, the aftermarket products that are the most watched by banks and state & Federal regulators are (in order): credit repair products, identity theft protection, vehicle etching, undercoating & rustproofing, credit insurance & GAP insurance, and extended warranties.
Some have little to no value at all and others (like extended warranties) are often sold during transactions where it makes no sense, like a short-term lease where the bumper-to-bumper manufacturer warranty already covers everything during the term. Even some major lenders like US Bank have put dealers on notice in recent years that they are looking carefully at all contracts. They are watching for inflated prices on aftermarket products, rate anomalies from borrower to borrower, and are requiring justifications from dealers for what they uncover.
How to keep your F&I department compliant AND profitable:
- Shift the focus of compensation for the F&I managers from commission to CSI-based pay. Many successful dealerships offer a salary & commission hybrid pay plan that keeps the staff less stressed and less likely to resort to unethical practices.
- Consider daily or weekly, random deal audits by management outside of the F&I department to insure all compliance issues are dealt with swiftly and procedures are being followed.
- If your dealership hasn’t already switched, try replacing the paper menu selling system with a computerized system that offers transparent pricing for all aftermarket products. Fewer chargebacks and higher CSI has been seen in dealers that use this method.
- Regular training in both regulatory compliance and a consultative sales approach can safeguard the dealership from falling victim to a F&I manager that could be putting their own personal financial desires ahead of the dealerships goals of doing business in an ethical way on every deal.
F&I managers doing business the ‘old way’ risk not only their jobs, but now fines and criminal charges. Simple changes in procedure AND company philosophy can prevent both while protecting the dealership’s reputation in the community.