America has an opportunity to expand automotive manufacturing and capture more of the investment, technology, and skilled employment behind every vehicle. Chinese automakers’ growing ambitions make that opportunity more urgent. They also raise a question our industry needs to answer carefully: What kind of investment strengthens American automotive competitiveness?
An American assembly plant can create jobs. But for manufacturers, dealers, and investors, “built in America” cannot be the only test. We must examine the supply chain, ownership, technology, and rules under which a company competes.
Build the industry behind the vehicle
I have spent much of my career around dealerships, been to automotive plants abroad and in the States, and know firsthand the strength of the automotive industry and its impact. Alabama offers a clear example of successful foreign automotive investment. Mercedes-Benz, Honda, Hyundai, Mazda, and Toyota have built operations that support suppliers, skilled workers, and communities beyond their plant gates.
Mercedes-Benz announced another $4 billion investment in Alabama in March 2026. Its Tuscaloosa County plant regularly exports about 60 percent of production. These are American-built vehicles competing globally, supported by longstanding investment and business relationships.
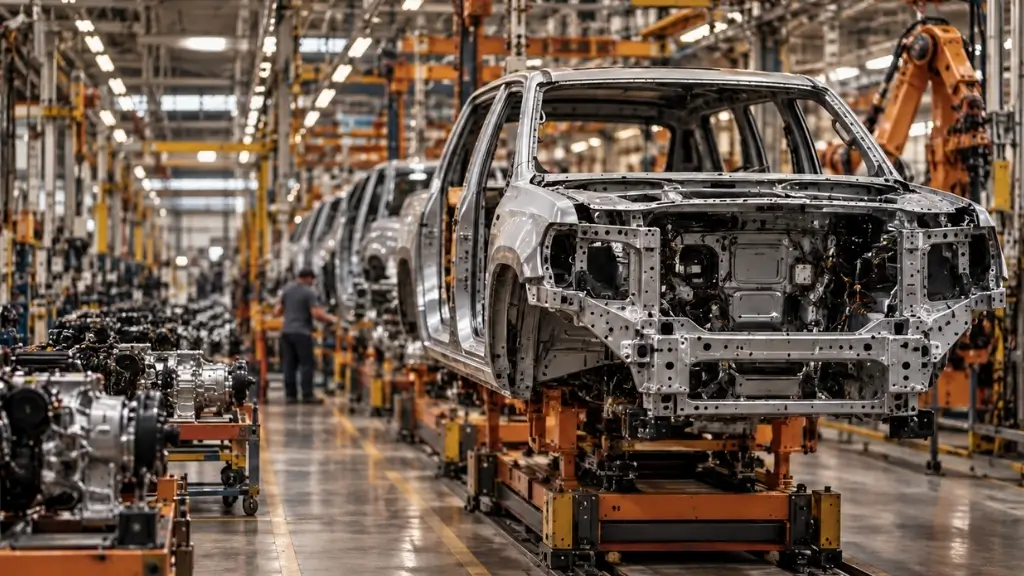
The next opportunity is to bring more of the manufacturing process here. Steelmaking, components, tooling, powertrains, battery cells, and engineering should all be part of that effort. Hyundai Steel’s $5.8 billion Louisiana mill project, targeting commercial production in 2029, would supply U.S. auto plants, including Hyundai’s Alabama operation. That moves investment further into the supply chain and gives American workers more of the value.
Final assembly matters. Lasting industrial strength requires deeper production capabilities. An operation that largely assembles imported kits while leaving critical technology and sourcing dependent on China deserves closer scrutiny.
The measure should be sustained domestic production, local supplier spending, and investment in American skills. A company’s headquarters tells only part of the story; the depth of its U.S. operations and its compliance with American standards tell us more.
Compete under comparable rules
Chinese automakers have developed real strengths in manufacturing efficiency, batteries, and engineering. The International Energy Agency has documented those advantages. American manufacturers must continue improving product quality and affordability rather than assume trade protections alone will preserve their position.
The concern is how much of the cost advantage reflects unfair practices. The Center for Strategic and International Studies estimated more than $230 billion in Chinese government support for the EV sector from 2009 through 2023. The European Commission found unfair subsidies and imposed countervailing duties on Chinese battery-electric vehicles in 2024.
U.S. trade officials have documented forced technology transfer and cyber theft. The Department of Labor has identified forced-labor risks in Chinese aluminum supply chains serving automakers. Those concerns require transparency across the industry, including established brands using the same suppliers.
Security also follows the technology. Under the Commerce Department’s connected-vehicle rule, restrictions beginning with model year 2027 cover certain China-linked software and connected-vehicle sales by manufacturers under Chinese ownership, control, or jurisdiction. The manufacturer restrictions can apply even to U.S.-built vehicles; separate hardware restrictions follow later. Domestic assembly does not automatically resolve those concerns.
What this means for dealership value
Dealers have substantial capital invested in facilities, technicians, and service capacity. Any new entrant must comply with applicable state franchise and retail laws. Its distribution model and commitment to warranty support also matter to customers and the businesses serving them.
Cox Automotive’s 2026 research found that deep discounts increased shoppers’ interest in Chinese vehicles and that 70 percent of surveyed dealers would change strategies if Chinese brands entered the U.S. market. Those findings warrant planning, though the effects would vary by franchise and market.
In buy-sell transactions, buyers evaluate the durability of future earnings. Product competitiveness, factory relationships, margins, and required investment influence what they will pay. Lower-priced competition could reduce expected earnings while greater uncertainty lowers the blue-sky multiple applied to those earnings. Together, those changes can materially affect dealership value.
Trade policy therefore belongs in acquisition planning, franchise selection, and succession discussions. Owners should assess how their manufacturers are strengthening domestic supply chains and positioning their products to compete.
America should enforce trade and security protections while making productive investment easier through predictable policy, reliable energy, and workforce training. Enforcement should address attempts to evade restrictions through third-party countries or corporate arrangements.
The objective should be to build more of vehicles here, develop more of the technology, and sell American-made products worldwide. That is how we strengthen American automotive leadership and protect the long-term value of the businesses behind it.
American innovation built the modern automotive industry and some of the finest vehicles in the world. We should not allow China to undercut that achievement through subsidies, unequal rules and market practice our own manufacturers would never be permitted to use.