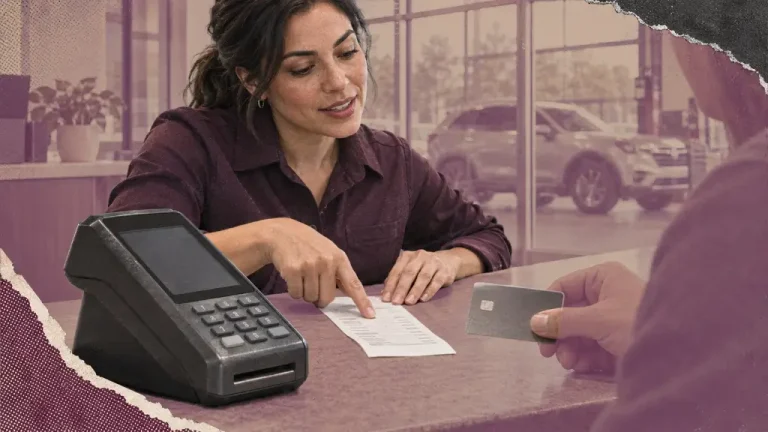
The simple convenience of credit card payments can have lasting implications for both dealers and customers. For customers, using a credit card is familiar and flexible. For dealerships, however, credit card processing requires considerable preparation and planning. Although processing credit cards comes with its share of complexities, dealers can take proactive steps to ensure they are protecting their bottom line while staying in compliance.
Understanding Surcharging Compliance
Surcharging is the practice of adding a fee to a customer’s credit card transaction to help offset the merchant’s cost of processing that payment. Dealerships apply surcharging structures in order to address rigid credit card fees and prevent unnecessary revenue loss.
The compliance that accompanies this practice is determined by various state and federal regulations, as well as card brand rules. These protections exist to ensure all customers are treated fairly when making a purchase and to guide business standards in the industry.
Common surcharge rules include:
- a mandate for dealerships to apply credit card surcharges consistently across all payment methods
- limits on surcharge amounts
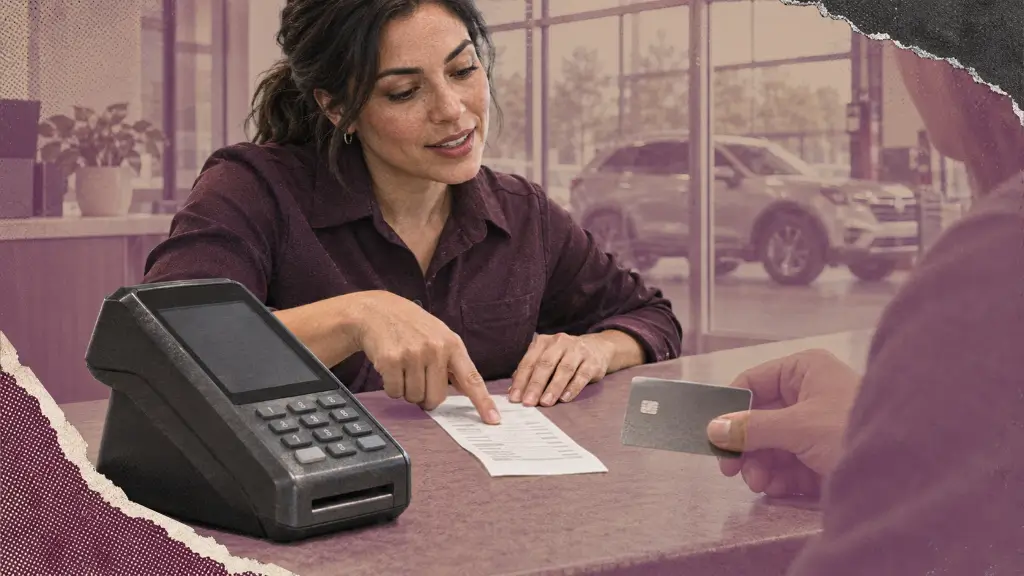
- compliant signage posted at payment terminals for customer transparency.
What’s at Risk?
Non-compliance can produce unnecessary operational risk in your dealership. The challenge of manually calculating each fee, in accordance with ever-changing regulations across multiple systems, increases the likelihood of error.
When surcharging falls out of compliance, large dealerships can face hundreds of thousands of dollars in penalties due to the volume of transactions. But the consequences can extend beyond regulatory penalties.
Furthermore, customer experience may be compromised. When a customer anticipates the end of a car sale approaching, they may be caught off guard when discovering an unexpected credit card fee tacked onto their payment.
Who Can Support You?
An expert dealer partner in surcharging compliance should lead with transparency and technically sound systems. When identifying a potential surcharging partner, there are several characteristics to consider:
Automation and Integrations: Alleviating the administrative lift of manually processing a surcharge will save you time, risk, and money in the long run. Automations should be able to correctly assess and apply surcharges across multiple data processing channels.
Clear Customer Communication: In compliance, providers must inform customers about surcharges through mandated signage, receipts, and online payment portals. For example, the payment processor must show both cash and credit prices upfront to customers.
Dealership Staff Training: Invest time and resources into dealership staff training to ensure they are fluent and current on surcharging regulations. Your selected surcharging partner should be able to provide comprehensive training sessions to support these efforts.
Solid Track Record: Your selected partner should be able to demonstrate their understanding of compliance through experience and active monitoring of compliance-related legislation.
Fraud Protection: Compliance with state regulations and reducing fraudulent disputes are critical in payment processing. myKaarma ensures compliance and offers 3D Secure Fraud Liability Shift, requiring two-factor authentication for online payments. This shifts the liability of fraudulent disputes away from the dealership to the customer and their bank.
Transforming Surcharging Compliance into Surcharging Strategy
Surcharging can save you considerable resources when applied correctly. When fees are legally and transparently processed, your profitability remains sound and customer feel respected in their car-buying experience.