If your dealership works in the subprime space at all, you already understand the challenges that come with these deals. Tighter restrictions on payment, income verification, and a sometimes hostile or uncomfortable exchange between F&I and the borrower.
How can this process be easier for both and still result in a car delivered and a decent PRU? Let’s take a look at 3 ways F&I can help make this already difficult buying scenario a little easier for everyone…
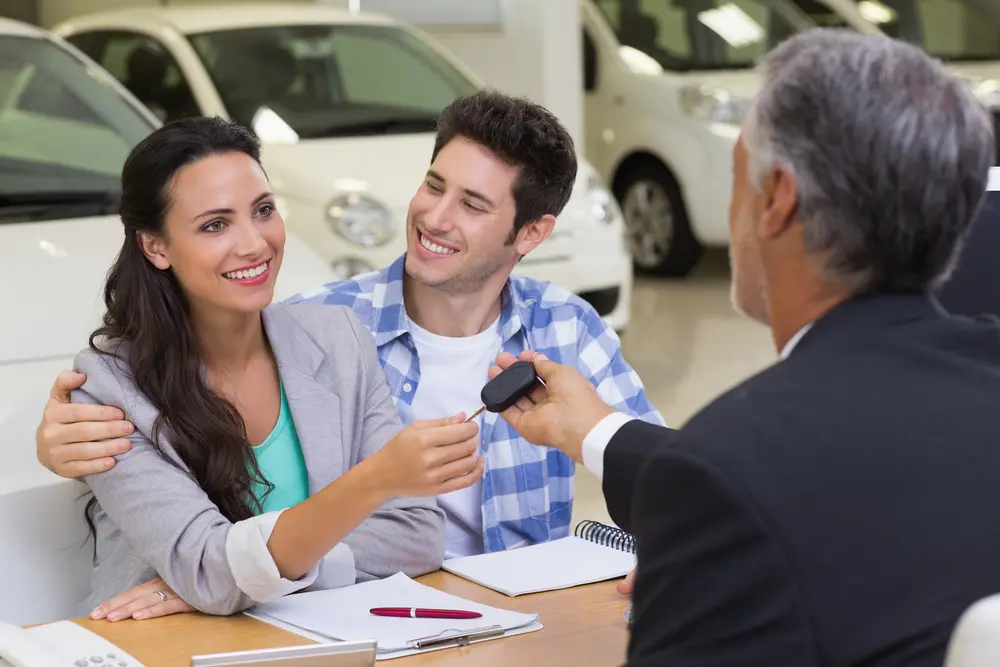
- Servant Attitude – Your role is to execute the paperwork, sell aftermarket products, and make sure the deal is airtight for the lender. With the subprime borrower, this entire process can be more difficult. The customer may not know how bad their credit is and if so, they can become hostile if this information is presented in a way that make them defensive.
If you as the F&I manager already know this presentation could go bad, then take steps ahead of time to ensure the borrower won’t get defensive. Do not talk down to them. Don’t treat them any differently than you would treat an A-paper buyer. Talk to them with respect and have all the tools you need to help walk them through their options. Show empathy and approach every subprime borrower as the person who can best help them drive off in the car they need.
- Drill Down on Income Verification – Stips are a pain but a necessary evil for all of your subprime lenders. Collect as much income information as you can. Don’t be afraid to ask the more uncomfortable questions regarding additional sources of income from child support, alimony, or other monthly sources that could help. Don’t take the initial credit application at face value. Many borrowers may not be aware what other income can help them qualify. Your job is to educate them on this process and help them create a favorable outcome with the lender.
- Be Creative – Even though there may be little room in the payment for product, don’t be afraid to be creative when positioning it to the buyer. Go through the same selling steps you would with any other A-paper buyer. Explain how credit life/A&H can help preserve their credit in case of job loss or injury. If they live in the city and have to park on the street, explain how GAP (if your store is allowed to sell it) can help make sure they are not paying out of pocket in case of a loss.
If you have asked all the right questions, you can still hold a solid PRU even with a subprime loan and do it in a way that reduces the chance for a chargeback. Maybe only one product will ‘fit’ with the payment…so make sure it is a product the borrower feels will help them the most.
If you treat the subprime borrower as a you would any other buyer first, the rest of the process should be easy. Your professionalism and empathy can go a long way to ensuring goodwill and repeat business from them as well as referrals in the future. Trust me, they will remember your kindness and servant attitude when they pay that car off and are ready for a new one.